CVM 193 and CVM 244: where sustainability reporting stands in Brazil
CVM 193 established adoption of the IFRS S1 and S2 standards. CVM 244 revised the timeline: adoption is voluntary. Even so, it remains the reference standard for investors, banks and the market.
Companies that trust Mangue Tech

Consulting + Platform
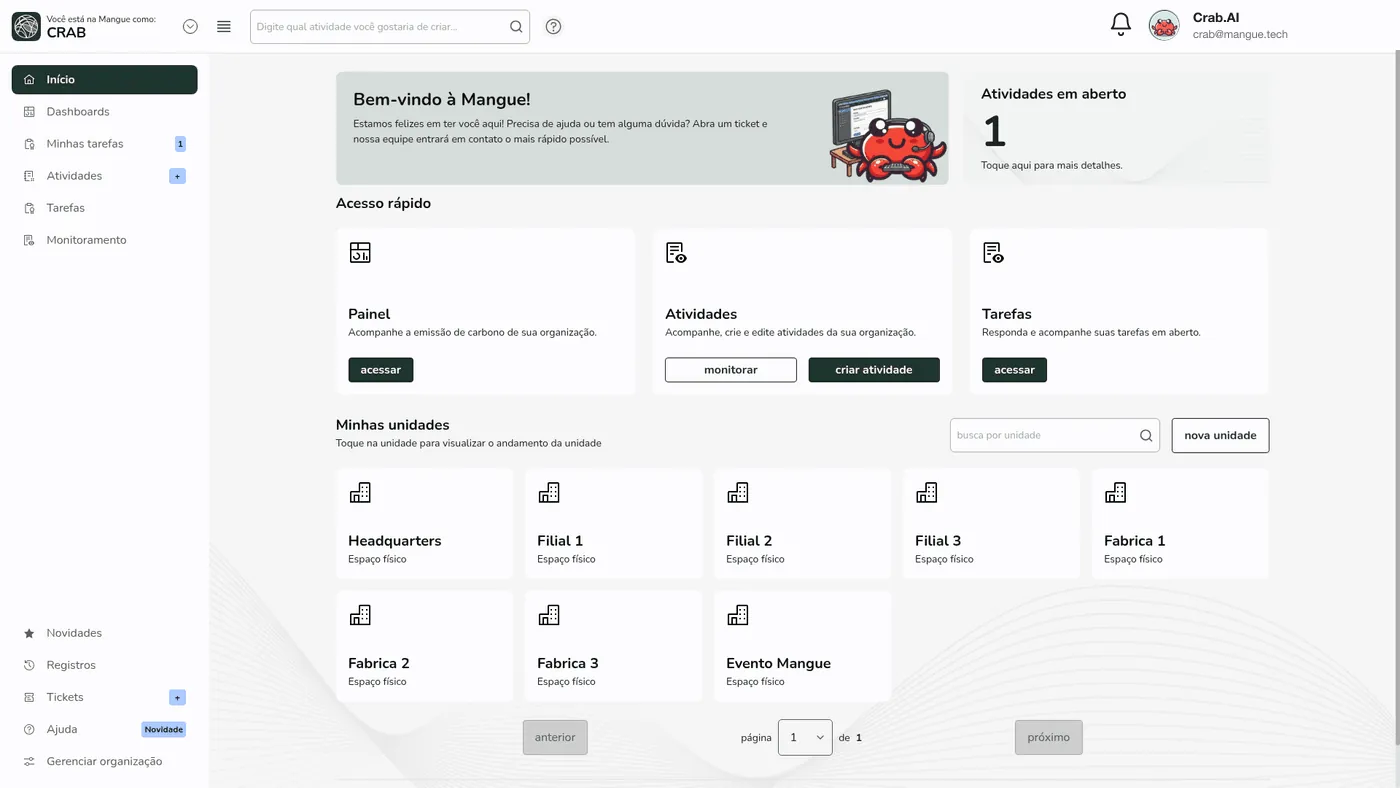
Operational data becomes auditable ESG indicators.
Specialist consulting that understands CVM 193. A platform that automates the calculation, versions the data and exports it in the format the regulator requires.
Consultoria
ESG data and compliance management, with a specialist who knows your sector.
Plataforma
Our own software, automating calculations, indicators and exports.
Auditable reports
GHG inventory, decarbonization plan and reports ready for the auditor.
Less time
Automated collection vs. manual spreadsheet.
Global frameworks
IFRS, CSRD, CBAM, GRI, SASB, GHG, CDP…
Emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent.
How Mangue works
4 steps. From diagnosis to an auditable report.
Diagnosis
Find out which ESG risks affect your business and what the regulator will require.
Estrutura
Organized data, defined processes and everything ready for any verification.
Operation
Emission calculations, decarbonization targets and continuous monitoring.
Auditable reports
Active compliance with IFRS, CSRD, CBAM, GRI, SASB and GHG Protocol.
Mangue deliverables for CVM 193
Every delivery is a complete package: consultant + platform + auditable report. Click to see how we apply it.
The framework
What it is, and why it matters.
In 2023 the CVM published Resolution 193, which brings the ISSB standards (IFRS S1 and S2) into the Brazilian capital market. Resolution 244, a later revision, made adoption voluntary. Listed companies keep the option of disclosing sustainability information in the standardized IFRS format.
Even as a voluntary standard, it remains the reference: international funds and banks use IFRS S1/S2 as the common vocabulary for ESG disclosure, and European clients under CSRD require data that maps to IFRS S2.
The disclosures cover governance, strategy, risk management and metrics/targets. When published, it is best presented alongside the financial statements and with assurance from an independent auditor. That raises ESG data quality to the level of financial information.
At scale
When the standard updates, the calculation engine is already up to date.
supported frameworks
GHG Protocol, CSRD, IFRS S2, CDP, GRI, SASB, CBAM, SBCE. One single database.
emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent. All versioned, with source, year and gas.
scopes covered
Scopes 1, 2, 3 and biogenic. Operational and financial. Everything goes in.
Aplicabilidade
Who it applies to.
- Listed companies registered with the CVM that choose to adopt the standard: voluntary after CVM 244, but a reference for investors and banks.
- Companies preparing for an IPO that need to show ESG maturity from the first report.
- Investment funds and asset managers that have to report portfolio sustainability under CVM 175.
- Large companies getting ahead of a likely return of mandatory reporting in the capital market.
How we deliver
From source to auditor.
We map the company's current disclosure and identify gaps against the IFRS S1 and S2 requirements set by CVM rules.
We structure the disclosures across the four pillars (governance, strategy, risk management, metrics), combining quantitative emissions data from the Mangue platform with qualitative information.
We deliver the disclosure draft ready for review by the independent auditor, in the format the CVM requires, cross-referenced to sector SASB and CDP.


The IFRS S1 & S2 Roadmap: the 12 decisions your CFO must make before 2027
A practical guide for CFOs, IR Directors, Controllers and Accounting. ~15 min read, straight to your inbox.