Brazilian Sustainable Taxonomy: criteria for green finance
The decree that defines which economic activities count as sustainable in Brazil. The basis for access to green credit lines, ESG bonds and tax incentives.
Companies that trust Mangue Tech

Consulting + Platform
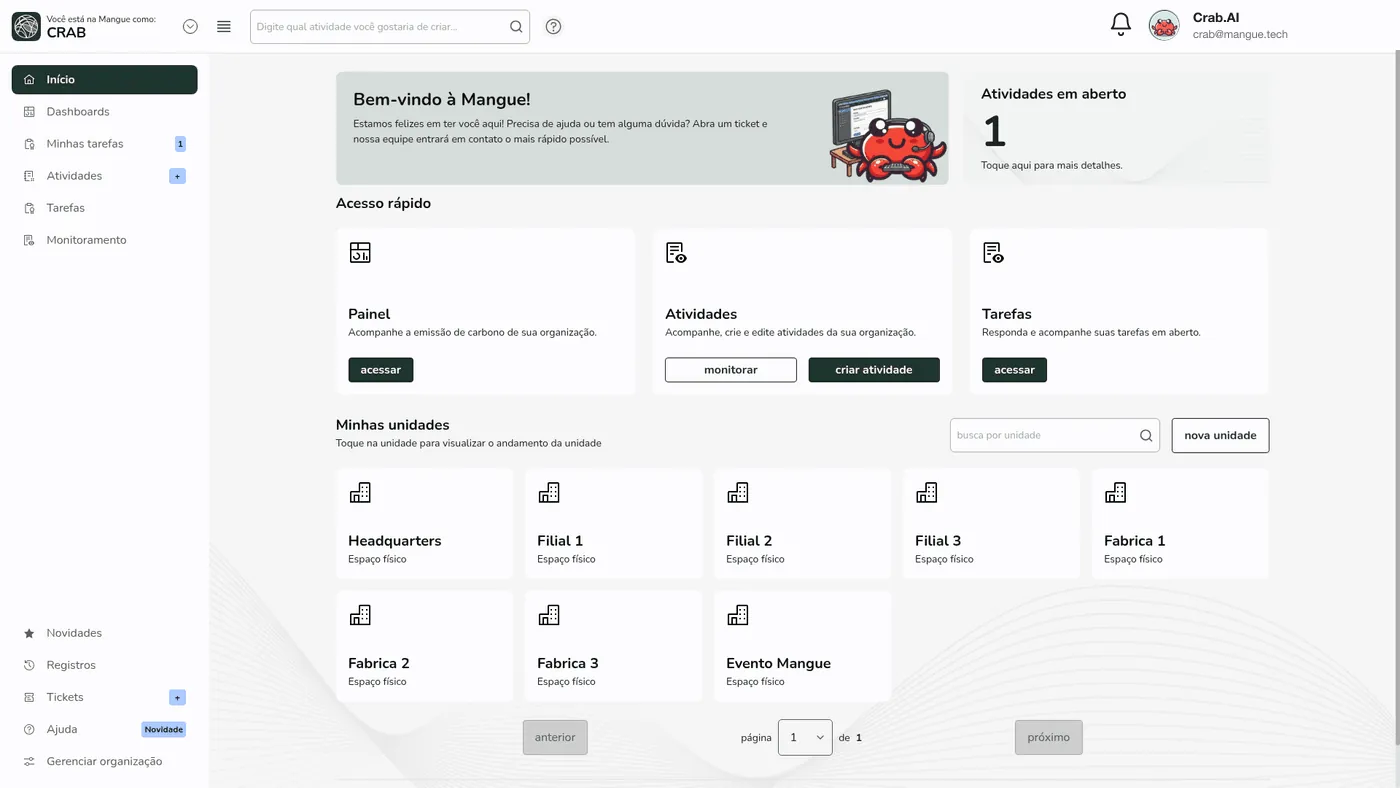
Operational data becomes auditable ESG indicators.
Specialist consulting that understands Taxonomia Brasileira. A platform that automates the calculation, versions the data and exports it in the format the regulator requires.
Consultoria
ESG data and compliance management, with a specialist who knows your sector.
Plataforma
Our own software, automating calculations, indicators and exports.
Auditable reports
GHG inventory, decarbonization plan and reports ready for the auditor.
Less time
Automated collection vs. manual spreadsheet.
Global frameworks
IFRS, CSRD, CBAM, GRI, SASB, GHG, CDP…
Emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent.
How Mangue works
4 steps. From diagnosis to an auditable report.
Diagnosis
Find out which ESG risks affect your business and what the regulator will require.
Estrutura
Organized data, defined processes and everything ready for any verification.
Operation
Emission calculations, decarbonization targets and continuous monitoring.
Auditable reports
Active compliance with IFRS, CSRD, CBAM, GRI, SASB and GHG Protocol.
Mangue deliverables for Taxonomia Brasileira
Every delivery is a complete package: consultant + platform + auditable report. Click to see how we apply it.
The framework
What it is, and why it matters.
The Brazilian Sustainable Taxonomy (TSB) is the classification system that defines which economic activities can be considered sustainable in the country. Modeled on the EU Taxonomy, it adapts the technical screening criteria to Brazilian conditions: biomes, energy mix and productive sectors.
The TSB sets environmental objectives (climate change mitigation, adaptation, sustainable use of water resources, circular economy, pollution prevention, biodiversity protection) and, for each activity, criteria for substantial contribution and do-no-significant-harm (DNSH).
In practice, the TSB will be the reference for issuing green bonds and sustainability-linked bonds, accessing green credit lines from BNDES and commercial banks, obtaining tax incentives for sustainable activities and classifying ESG funds at the CVM.
At scale
When the standard updates, the calculation engine is already up to date.
supported frameworks
GHG Protocol, CSRD, IFRS S2, CDP, GRI, SASB, CBAM, SBCE. One single database.
emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent. All versioned, with source, year and gas.
scopes covered
Scopes 1, 2, 3 and biogenic. Operational and financial. Everything goes in.
Aplicabilidade
Who it applies to.
- Companies seeking green finance (green bonds, sustainability-linked loans, BNDES lines) that have to show eligibility under the TSB.
- Banks and financial institutions building green financial products that need to classify their clients' activities.
- ESG bond issuers that need a second-party opinion based on a recognized taxonomy.
- Construction, renewable energy and infrastructure companies that benefit from tax incentives for activities classified as sustainable.
How we deliver
From source to auditor.
We map the company's economic activities against the TSB criteria, identifying which revenue and investments are eligible.
We assess compliance with the substantial contribution and DNSH criteria for each activity, documenting evidence and gaps.
We deliver the taxonomy alignment report, with the share of revenue, capex and opex that is eligible and aligned, ready for bond issues or financing applications.

The IFRS S1 & S2 Roadmap: the 12 decisions your CFO must make before 2027
A practical guide for CFOs, IR Directors, Controllers and Accounting. ~15 min read, straight to your inbox.