TNFD: nature-related financial disclosures
It complements TCFD with a focus on dependencies and impacts on biodiversity. Adoption is growing fast, already required under ESRS E4.
Companies that trust Mangue Tech
Consulting + Platform
Operational data becomes auditable ESG indicators.
Specialist consulting that understands TNFD. A platform that automates the calculation, versions the data and exports it in the format the regulator requires.
Consultoria
ESG data and compliance management, with a specialist who knows your sector.
Plataforma
Our own software, automating calculations, indicators and exports.
Auditable reports
GHG inventory, decarbonization plan and reports ready for the auditor.
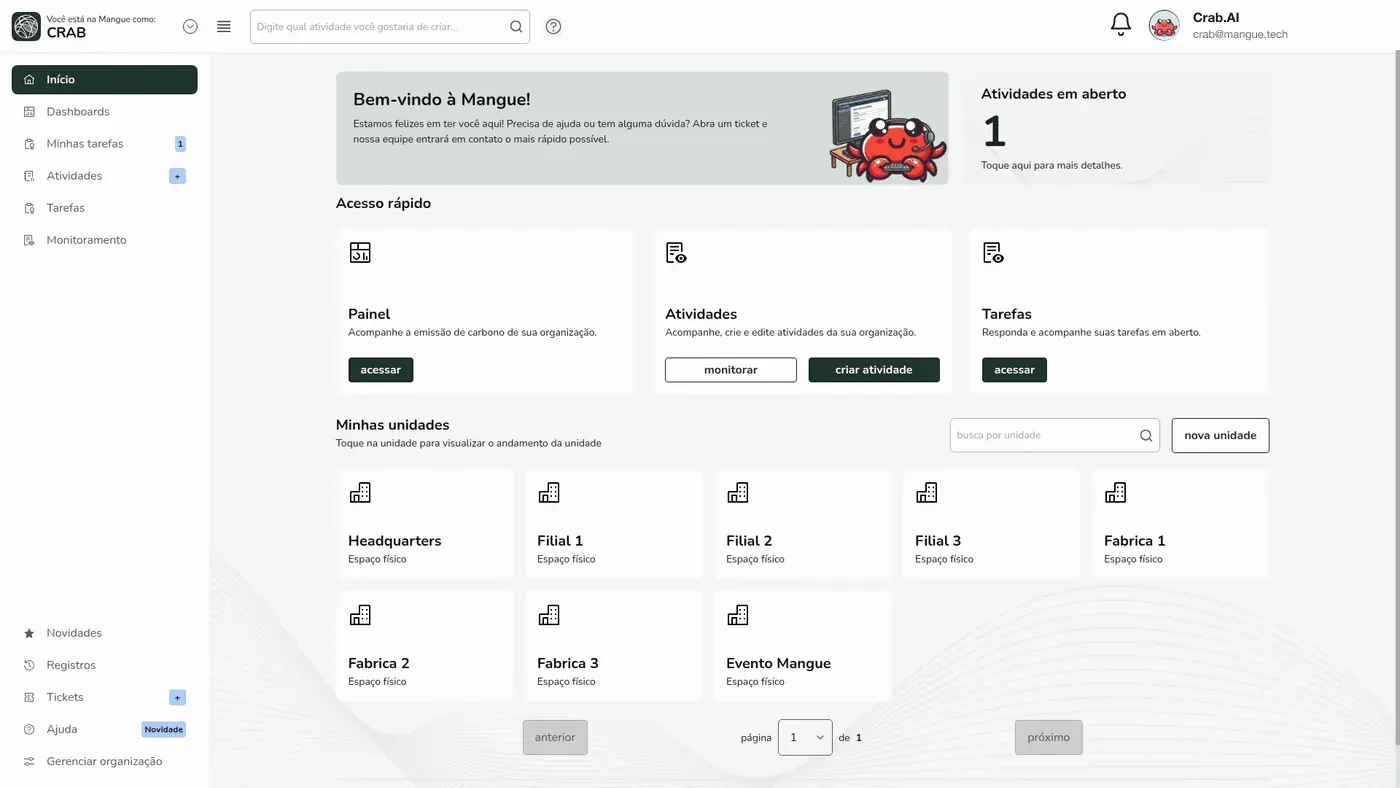
Less time
Automated collection vs. manual spreadsheet.
Global frameworks
IFRS, CSRD, CBAM, GRI, SASB, GHG, CDP…
Emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent.
How Mangue works
4 steps. From diagnosis to an auditable report.
Diagnosis
Find out which ESG risks affect your business and what the regulator will require.
Estrutura
Organized data, defined processes and everything ready for any verification.
Operation
Emission calculations, decarbonization targets and continuous monitoring.
Auditable reports
Active compliance with IFRS, CSRD, CBAM, GRI, SASB and GHG Protocol.
Mangue deliverables for TNFD
Every delivery is a complete package: consultant + platform + auditable report. Click to see how we apply it.
The framework
What it is, and why it matters.
TNFD (Taskforce on Nature-related Financial Disclosures) is the global framework for disclosing nature-related risks and opportunities. Launched in September 2023, it follows the same four pillars as TCFD (governance, strategy, risk management, metrics and targets), applied to dependencies and impacts on biodiversity, water, soil and ecosystems.
The LEAP approach guides companies through their interfaces with nature: Locate where assets and operations are, Evaluate dependencies and impacts, Assess material risks and opportunities, and Prepare the disclosure.
TNFD is already referenced in ESRS E4 (biodiversity and ecosystems) under the European CSRD, in CDP Forests and in GRI 304. Regulation is converging: companies that report to TNFD will be ready for the biodiversity requirements being folded into several frameworks.
TNFD was built on the model of TCFD (Task Force on Climate-related Financial Disclosures), created by the Financial Stability Board (FSB) to guide the disclosure of climate risks. TCFD was disbanded in October 2023 after fulfilling its mandate, and monitoring of climate disclosures passed to the IFRS Foundation. The TCFD recommendations are incorporated into the ISSB's IFRS S2.
The four pillars are the same in both: governance, strategy, risk and impact management, and metrics and targets. What changes is the subject. TCFD looks at climate. TNFD looks at nature and adds the notion of impact: beyond how nature affects the company, it asks how the company affects nature. There are 14 recommended disclosures, including the 11 TCFD disclosures adapted for nature.
For Brazilian companies, TNFD matters most in sectors that depend on water, soil and biodiversity, such as agribusiness, mining, energy and forestry. Companies already using the TCFD or IFRS S2 structure can reuse governance, risk management processes and part of the metrics.
At scale
When the standard updates, the calculation engine is already up to date.
supported frameworks
GHG Protocol, CSRD, IFRS S2, CDP, GRI, SASB, CBAM, SBCE. One single database.
emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent. All versioned, with source, year and gas.
scopes covered
Scopes 1, 2, 3 and biogenic. Operational and financial. Everything goes in.
Applicability
Who it applies to.
- Companies operating in ecologically sensitive areas (protected biomes, watershed areas, coastal zones).
- TNFD Adopters that have committed to reporting under the framework.
- Companies reporting under CSRD that have to meet ESRS E4 (biodiversity and ecosystems).
- Financial institutions exposed to nature-dependent industries (agribusiness, mining, forestry).
- Companies that answer CDP Forests or Water Security and want one integrated nature framework.
How we deliver
From source to auditor.
We apply the LEAP approach to identify the company's interfaces with nature: locating assets, evaluating dependencies and impacts, and mapping risks and opportunities.
We structure the disclosures across the four TNFD pillars, combining geospatial location data with qualitative information on biodiversity governance and strategy.
We deliver the aligned TNFD report, cross-referenced to ESRS E4, CDP Forests and GRI 304, maximizing the reuse of information across frameworks.
The IFRS S1 & S2 Roadmap: the 12 decisions your CFO must make before 2027
A practical guide for CFOs, IR Directors, Controllers and Accounting. ~15 min read, straight to your inbox.
We got your info! Camila will send you the IFRS S1 & S2 Roadmap by email shortly.
Frequently asked questions