CBAM: the EU carbon border adjustment mechanism
Exporters to the EU have to declare the emissions embedded in their products. Mangue Tech calculates and reports them as CBAM requires.
Companies that trust Mangue Tech
Consulting + Platform
Operational data becomes auditable ESG indicators.
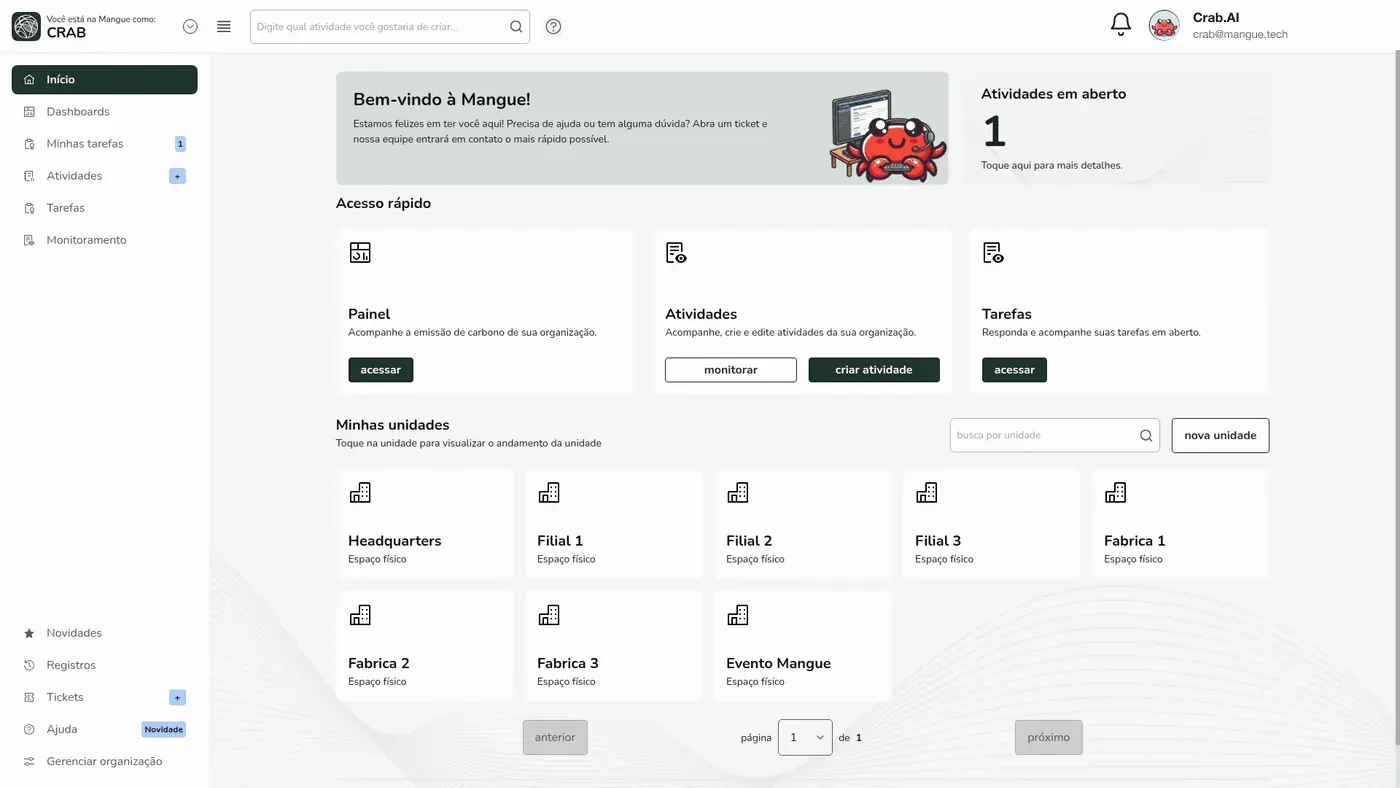
Specialist consulting that understands CBAM. A platform that automates the calculation, versions the data and exports it in the format the regulator requires.
Consultoria
ESG data and compliance management, with a specialist who knows your sector.
Plataforma
Our own software, automating calculations, indicators and exports.
Auditable reports
GHG inventory, decarbonization plan and reports ready for the auditor.
Less time
Automated collection vs. manual spreadsheet.
Global frameworks
IFRS, CSRD, CBAM, GRI, SASB, GHG, CDP…
Emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent.
How Mangue works
4 steps. From diagnosis to an auditable report.
Diagnosis
Find out which ESG risks affect your business and what the regulator will require.
Estrutura
Organized data, defined processes and everything ready for any verification.
Operation
Emission calculations, decarbonization targets and continuous monitoring.
Auditable reports
Active compliance with IFRS, CSRD, CBAM, GRI, SASB and GHG Protocol.
Mangue deliverables for CBAM
Every delivery is a complete package: consultant + platform + auditable report. Click to see how we apply it.
Frameworks we apply
The framework
What it is, and why it matters.
The Carbon Border Adjustment Mechanism (CBAM) is the European Union instrument that charges for the carbon intensity embedded in imported products. From October 2023 to December 2025, European importers only declared those emissions; the financial charge has applied since 2026.
The sectors covered in the first phase are iron and steel, aluminum, cement, fertilizers, electricity and hydrogen. The scope is expected to expand to chemicals and polymers.
Brazilian exporters have to supply direct and indirect emissions data for each installation. Without that data, the European importer falls back on the default values the EU publishes by product and country of origin. Using verified actual emissions is usually more favorable than the default value.
In practice, CBAM is a carbon price charged at the border. It aligns the carbon cost of imported goods with what European producers already pay in the EU carbon market, the EU ETS. Its stated goal is to prevent carbon leakage, when production moves to countries with weaker climate rules.
CBAM has two phases. In the transitional phase, from October 2023 to December 2025, importers only reported embedded emissions, in quarterly reports, with no payment. In the definitive phase, from 2026, importers must hold authorized CBAM declarant status, declare the year's embedded emissions and surrender the corresponding CBAM certificates, priced in line with the EU ETS. The effective charge is phased in: it grows until 2034 as the EU withdraws free allocation of allowances to European industry.
Brazilian exporters do not pay CBAM, but they hold the data. The importer will ask for: embedded emissions per product, direct and, where applicable, indirect, in tCO₂e per tonne; installation data, such as location, production route and precursors used; and the carbon price paid in the country of origin, if any. In the definitive phase, actual emissions require independent verification by an accredited verifier. Without it, default values apply.
At scale
When the standard updates, the calculation engine is already up to date.
supported frameworks
GHG Protocol, CSRD, IFRS S2, CDP, GRI, SASB, CBAM, SBCE. One single database.
emission factors
IPCC, DEFRA, MCTI, EPA, Ecoinvent. All versioned, with source, year and gas.
scopes covered
Scopes 1, 2, 3 and biogenic. Operational and financial. Everything goes in.
Applicability
Who it applies to.
- Steelmakers and metal producers that export iron, steel or aluminum to the EU.
- Cement, fertilizer and hydrogen producers with European customers.
- Power generators that export electricity to EU member states.
- Any exporter whose European buyers ask for embedded emissions data to comply with CBAM.
How we deliver
From source to auditor.
We map each exporting installation and set system boundaries following the CBAM methodology (Implementing Regulation 2023/1773).
We calculate direct and indirect emissions per tonne of product, with verifiable factors and a complete audit trail.
We organize embedded emissions by installation and product in the format the authorized CBAM declarant uses to report in the CBAM Registry, with the trail ready for independent verification.
The IFRS S1 & S2 Roadmap: the 12 decisions your CFO must make before 2027
A practical guide for CFOs, IR Directors, Controllers and Accounting. ~15 min read, straight to your inbox.
We got your info! Camila will send you the IFRS S1 & S2 Roadmap by email shortly.
Frequently asked questions